If the main purpose of investing is keeping money relatively safe, cryptocurrency and a bank Fixed Deposit (FD) belong to completely different risk categories. An FD offers a predetermined interest rate and repayment terms, while cryptocurrency prices can rise or fall sharply within a short period. Someone investing ₹2 lakh in an FD generally knows the maturity amount in advance, whereas ₹2 lakh invested in crypto could be worth considerably more—or much less—when the money is needed.
For Indian investors prioritising capital stability, predictable returns and short- to medium-term goals, an FD is generally the more suitable choice. Cryptocurrency may offer much higher growth potential, but it should be treated as a high-risk asset rather than an alternative to safe savings.
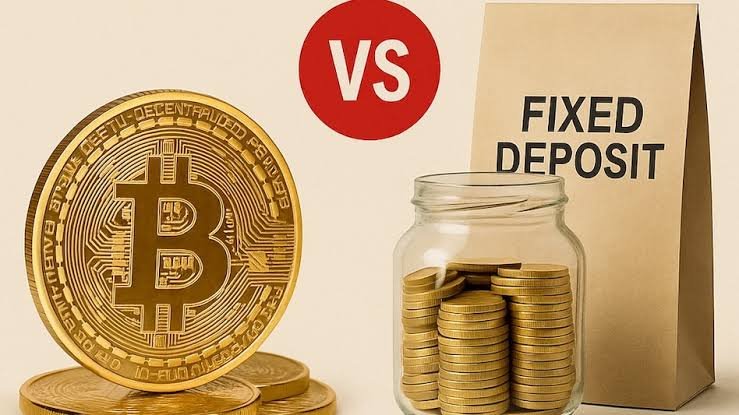
Cryptocurrency vs Fixed Deposit: Quick Comparison
| Factor | Fixed Deposit | Cryptocurrency |
| Capital stability | Relatively high | Very low |
| Return predictability | Predetermined | Highly unpredictable |
| Price volatility | None during normal FD tenure | Extremely high |
| Regular income option | Available with some FDs | Usually no traditional interest |
| Investment duration | Fixed tenure selected by investor | No fixed tenure |
| Premature access | Usually possible with conditions | Can generally be sold quickly |
| Deposit protection | Eligible bank deposits get protection subject to limits | No deposit insurance protection |
| Growth potential | Moderate | Potentially very high |
| Risk level | Low to moderate depending on institution | Very high |
Fixed Deposits Are Designed for Predictability
An FD is one of the simplest investment products used by Indian households.
You deposit a fixed amount with a bank or another eligible institution for a chosen period. The applicable interest rate is normally known when the deposit is booked.
Suppose you invest ₹3 lakh for two years.
You can estimate how much interest the deposit will earn and approximately how much money will be available at maturity.
This predictability makes FDs useful when the amount will be required for a known purpose.
Crypto offers no comparable certainty.
Cryptocurrency Can Experience Large Price Falls
Cryptocurrency attracts investors because digital assets can sometimes appreciate rapidly.
The same characteristic creates significant risk.
A cryptocurrency can experience a major correction even after a strong rally. There is no guaranteed maturity value or minimum return.
Imagine investing money that will be required for college fees one year later.
If crypto prices fall sharply just before the payment is due, you may need to sell at a large loss.
For this reason, money needed for essential or near-term goals should generally not depend on highly volatile assets.
FD Returns Are Known, but Usually Limited
The advantage of an FD is also its limitation.
When the interest rate is fixed, your return generally does not increase simply because financial markets perform exceptionally well.
Suppose your FD pays a predetermined annual rate.
Even if the stock market or cryptocurrency market rises dramatically during that period, your agreed FD return remains broadly unchanged.
For investors seeking aggressive long-term wealth creation, this may feel unattractive.
However, the objective of an FD is normally stability rather than maximum growth.
Cryptocurrency Has Much Higher Return Potential
There is no denying that certain cryptocurrencies have historically experienced exceptional periods of growth.
An investor buying at a favourable price may potentially earn returns far above normal FD interest rates.
But high return potential comes with high uncertainty.
You cannot reasonably assume that a crypto asset will appreciate by a particular percentage every year.
Past gains also do not guarantee that the same asset will remain valuable over the next five, ten or twenty years.
Therefore, comparing FD interest with the best historical crypto returns can create a misleading picture.
Bank FDs Have Deposit Insurance Protection
Eligible bank deposits in India receive deposit insurance protection through the applicable deposit-insurance framework, subject to prescribed limits and conditions.
Currently, eligible deposits are insured up to ₹5 lakh per depositor per bank in the same right and capacity, including principal and interest.
This protection covers eligible savings, current, recurring and fixed deposits with insured banks.
It should not be misunderstood as unlimited government protection for every FD product.
For example, deposits with certain non-bank entities do not receive the same deposit-insurance protection simply because they are marketed as fixed deposits.
Cryptocurrencies do not receive this type of bank-deposit insurance.
Liquidity Works Differently
Cryptocurrency can generally be sold quickly when active markets are available.
An FD has a specified maturity date, but many banks permit premature withdrawal subject to their terms and possible interest adjustments or penalties.
This creates an interesting difference.
Crypto may offer faster market liquidity, but the price available when you need the money could be much lower than your purchase price.
An FD may have withdrawal conditions, but its value does not fluctuate every minute according to market sentiment.
For emergency money, liquidity and capital stability should be considered together.
Tax Can Reduce Returns From Both
Indian investors should compare investments based on what remains after tax.
FD interest is generally taxable according to the investor’s applicable income-tax position.
Virtual digital assets follow a separate tax framework in India. Crypto gains are subject to special taxation rules, and applicable transactions can also involve tax-deduction requirements.
Tax rules can change, so investors should check the latest provisions before making a major investment or sale.
A crypto asset showing a large headline gain may therefore provide a different return after taxes and transaction costs are considered.
FDs Are Better for Short-Term Financial Goals
Suppose you need money in two years for:
- Higher education fees
- A vehicle purchase
- A planned family expense
- A house down payment
- Another known financial commitment
In such situations, protecting the required amount may be more important than trying to generate the highest possible return.
An FD can provide greater certainty about how much money will be available.
Cryptocurrency is generally unsuitable for a goal where a substantial decline shortly before the deadline would create financial difficulty.
Inflation Is an Important FD Limitation
Safety alone is not enough for every long-term objective.
If inflation increases faster than your post-tax FD return, the real purchasing power of the investment may grow slowly or even decline.
For example, money intended for retirement 25 years from now usually requires consideration of long-term growth as well as safety.
This is why investors often use FDs for the safer part of their finances while considering other diversified investments for long-term growth.
Crypto should not automatically become the solution to inflation simply because its potential return is higher. Higher expected growth comes with much greater risk.
Cryptocurrency Also Has Security and Platform Risks
Crypto investors face risks beyond price movements.
These can include fraudulent projects, phishing, loss of account access, wallet-related mistakes and problems involving platforms used to hold or trade digital assets.
FD investors also need to protect online banking credentials, but the product itself operates within an established banking structure.
Anyone choosing crypto should therefore understand both market risk and the technical risks involved in holding digital assets.
Which Is Better for Safe Investment?
If safety is the main priority, a suitable bank FD is generally far more appropriate than cryptocurrency.
FDs provide predictable interest, lower volatility and a clearer maturity structure. Eligible bank deposits also receive deposit-insurance protection within prescribed limits.
Cryptocurrency belongs to a different category. It may offer significantly higher returns, but it can also lose a substantial amount of value.
An investor should therefore avoid replacing emergency savings or money needed for important near-term goals with cryptocurrency merely because recent returns appear attractive.
The better choice depends on the purpose of the money: use safer investments when capital protection matters most, and approach high-risk assets only with money you can afford to expose to substantial fluctuations.
FAQs
Q1. Is cryptocurrency safer than a Fixed Deposit?
A: No. Cryptocurrency is generally much more volatile than an FD and can experience large losses. A bank FD is usually more suitable when capital stability is the main objective.
Q2. Can cryptocurrency give higher returns than an FD?
A: Yes, cryptocurrency can potentially deliver much higher returns, but it also carries substantially higher risk. There is no guaranteed crypto return or maturity value.
Q3. Is FD money completely risk-free?
A: No investment should automatically be described as completely risk-free. Eligible deposits with insured banks receive deposit protection up to the prescribed limit, but investors should still check the institution and product before depositing money.
Q4. Should beginners choose an FD or cryptocurrency?
A: Beginners seeking safety, predictable returns or money for short-term goals may find an FD more appropriate. Cryptocurrency should be approached as a high-risk asset and not as a replacement for emergency savings or essential financial reserves.